The SEC issued Memorandum Circular No. 26, Series of 2026 (MC 26), on Sept. 1, amending accreditation guidelines for auditing firms and external auditors under Revised Rule 68 of the Securities Regulation Code.
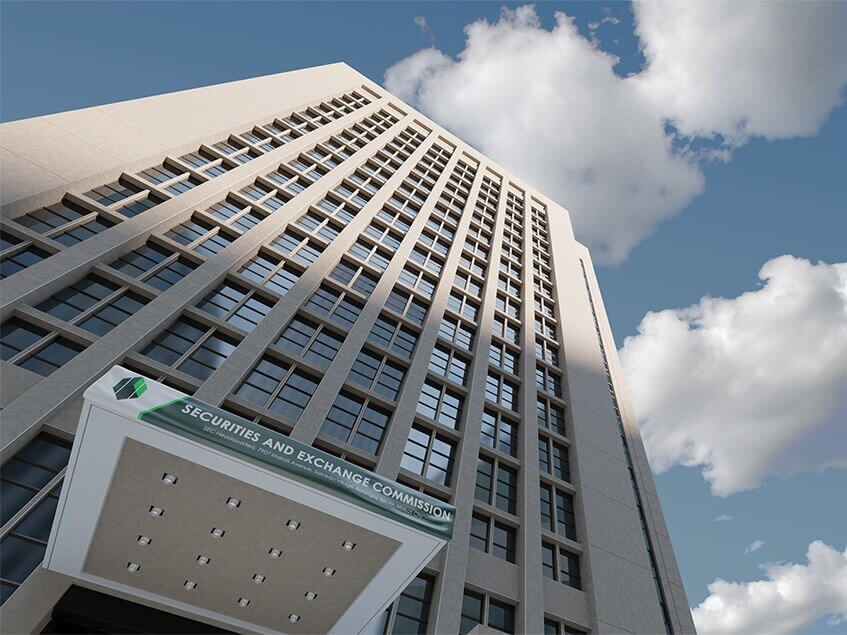
The new rules expand the SEC’s oversight to auditors of government contractors while raising qualification and track-record requirements and imposing stricter standards in evaluating applications for accreditation.
“High-quality audits serve as a foundation of transparency in capital markets, fostering public trust in the financial system,” SEC Chair Francis Lim said.
“By tightening our accreditation standards and extending oversight to auditors of major government contractors, we are reinforcing accountability, ensuring that public funds and investors’ hard-earned money are protected by rigorous and independent financial reporting,” he added.
Government contracts
The SEC accredits auditing firms and independent auditors under three categories—Groups A, B and C—depending on the entities they are qualified to audit.
MC 26 expands the coverage of Group A and Group B auditors to companies with government contracts involving the procurement of goods and consulting services or infrastructure projects.
The requirement covers contracts with the national government and its instrumentalities, including government-owned or -controlled corporations, state universities and colleges, and local government units.
Corporate general contractors with a single government contract exceeding P750 million, or cumulative government contracts of more than P1 billion, will be required to engage Group A independent auditors.
Contractors with a single government contract worth P400 million to P750 million, or cumulative contracts worth P500 million to P1 billion, must engage Group B independent auditors.
The accredited external auditor must remain engaged until the projects have been fully completed or delivered.
Covered companies will also be required to submit a notarized schedule containing the descriptions, costs and status of their government projects. The schedule must be covered by an auditor’s report.
Higher standards
The SEC also raised the minimum track-record requirements for auditors seeking accreditation across all three groups.
Group A applicants must have at least five corporate clients with total assets of at least P100 million each, double the previous P50-million asset threshold.
Group B applicants must have at least five corporate clients with assets of at least P50 million each. Previously, applicants needed three corporate clients with total assets of at least P20 million.
For Group C, applicants must have at least five corporate clients with assets of at least P5 million each, compared with the previous requirement of three corporate clients.
The changes are intended to ensure that auditors handling SEC-regulated entities have sufficient experience and an established track record.
Stricter screening
MC 26 also expands the grounds for outright denial of accreditation applications, adding nine circumstances to existing violations involving gross negligence and lack of auditor independence.
Among the additional grounds are misrepresentation or concealment of information during the evaluation process and issuing an unqualified audit opinion even when a client used an incorrect accounting framework that resulted in material misstatements.
Accreditation may also be denied upon the discovery of six or more material findings in a single set of financial statements or when auditors fail to maintain their independence, including cases in which they directly prepared the financial statements they audited.
For Group A and Group B applications, an applicant may secure five-year accreditation only when the evaluation of the audited financial statements of each client shows no material findings.
For Group A, minor findings must not exceed two items for each set of audited financial statements, while Group B applicants may have no more than three minor findings.
The requirements covering audits of annual or interim financial statements will apply to fiscal years or periods ending on or after June 30, 2027. The other provisions of MC 26 will take effect after publication. —Ed: Corrie S. Narisma